
Ask ten stakeholders whether an employee store is a good idea, and you will likely get ten variations of yes. Ask who pays for the merchandise and who ultimately subsidizes the program, and the room gets quiet. That is the moment a company store project either gains a clear direction or drifts into assumptions that surface later as budget overruns, catalog disagreements, and unexpected work for HR.
This post breaks down the three honest ways to fund an employee store: the company pays and treats merchandise as a benefit, employees pay a set price while the company absorbs setup and management, or a hybrid points or allowance model funds a fixed amount per person. We will compare what each model does to catalog selection, inventory risk, and administrative load, then walk through the tax and accounting questions to settle before launch. You will also get a checklist of decisions to make before anyone designs the store, and a look at where a single-source business partner like OneStop Northwest fits. The through line is simple: choose the funding model first, then build.
Why the Funding Model Has to Be Chosen Before the Store Is Designed
Most company store debates start with product questions: what should we offer, what does the logo look like. They end with a money question nobody planned for: who actually pays for the merchandise. Answer that first. Catalog breadth, order minimums, embroidery, stock versus made-to-order, and shipping all change based on whether the company or the employee is the buyer, so design decisions lock in funding decisions. Funding first also keeps the catalog honest. A company-funded benefit store and an employee-purchase store can carry the same products while supporting different assortments without looking like a bait and switch. Store policies for employees are easier to write and defend once the model is settled, because eligibility, discount rules, and redemption limits flow from who pays. This is the first milestone in any realistic plan to launch an employee company store in 90 days. Build before deciding and you will likely rebuild, at greater cost in time and internal goodwill.
The Three Funding Models at a Glance
Once funding is settled, three models do most of the work. Each relocates cost rather than removing it.
- Company-pays benefit: the organization funds the merchandise and treats the store as a benefit rather than a purchase channel.
- Employee-pays: employees buy at a set price while the company absorbs setup, store technology, and ongoing management.
- Hybrid points or allowance: the company funds a fixed amount per person, and employees spend that allowance inside the store.
| Dimension | Company-pays | Employee-pays | Points or allowance |
|---|---|---|---|
| Who pays | Company | Employee | Company, fixed per person |
| Cash exposure | High | Low | Medium, fixed |
| Administrative load | Medium | Medium | High |
| Catalog control | Company | Shared | Company sets the band |
| Inventory risk | Company | Varies | Shared |
This table is a discussion framework for internal meetings, not a cost benchmark or a quoting tool.
If the store structure itself is still open, company store, team store, and employee portal models serve different goals and pair with different funding choices. Each model is examined in turn below.
Model One: Company Pays and Treats Merchandise as a Benefit
Under the benefit model, the organization sets a merchandise budget and employees order against it rather than paying out of pocket. That makes it the highest cash exposure of the three, and the number moves with headcount rather than with demand: add fifty people and the commitment grows whether or not anyone orders.
Catalog discipline carries more weight here than in either other model, because every item added is a direct spend item. Narrow, role-relevant selections tend to outperform wide lifestyle catalogs. Inventory decisions also land on the organization, which makes stock versus made-to-order consequential and favors low or no minimum programs.
Administration is moderate but front-loaded. Budget ownership, eligibility rules, and approval flows get defined once; after that, an online company store handles fulfillment. It fits best with uniforms and safety apparel, onboarding kits, recognition programs, and organizations that want brand consistency enforced at the point of order.
Model Two moves the product cost to employees instead, which changes what the store is for.
Model Two: Employees Pay, the Company Absorbs Setup and Management
Where Model One commits cash to merchandise, Model Two shifts the money to infrastructure. Employees buy at a set price while the organization funds the store platform, decoration setup, and ongoing management. Direct merchandise spend is the lowest of the three models, which makes it the easiest to get approved in a tight budget cycle.
The cost does not disappear; it moves to administration and program integrity. Pricing decisions, margin questions, discount rules, and exception handling all need a named owner.
Because employees self-select, the catalog can run broader. The price has to feel fair, though, or participation quietly drops and the store becomes a cost with no benefit.
Inventory risk sits with the organization or the fulfillment partner depending on how the program is structured, so write the stock policy before launch. This model fits spirit wear, voluntary branded apparel, and organizations wanting a convenience channel without a merchandise budget line. A managed partner can carry much of that setup burden, as this guide to setting up a school spirit store illustrates.
Model Three: Hybrid Points or Allowance Programs
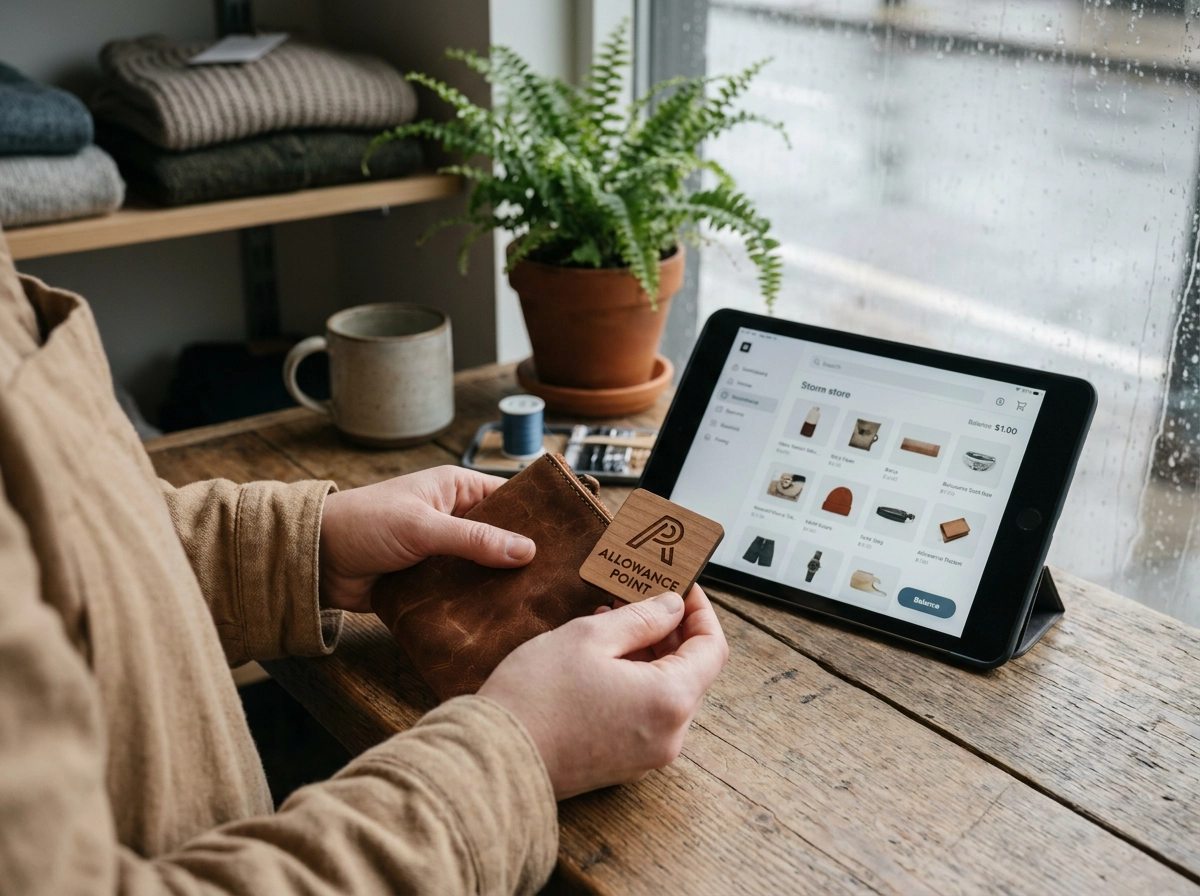
If Model Two puts the purchase decision in employees’ hands, the hybrid model puts the budget there instead. The company commits a fixed amount per person, and employees spend that allowance inside the store. Because total commitment equals headcount times allowance, not demand, forecasting and approvals get simpler. That predictability is the model’s main argument.
Complexity lives in the mechanics. Write them as store policies for employees, not platform defaults: how points are issued, when they expire, whether they carry over, and what happens at separation. Reconciliation needs a named owner. Unused balances, partial redemptions, and mid-year hires each need a documented answer before launch.
The allowance also sets the catalog ceiling. A balance that cannot buy anything meaningful reads as a broken benefit. This model fits milestone recognition, safety and wellness incentives, new-hire welcome allowances, and multi-location employers needing one consistent benefit. Where allowances support uniforms or recurring apparel, run them through managed apparel programs rather than one-off orders.
Next, those choices reshape catalog, inventory, and HR.
What Each Model Does to Catalog, Inventory, and HR
With points settled, the downstream effects become clearer. Catalog selection follows the funding rule: company-pays rewards curation and discipline, employee-pays rewards broad appeal and fair pricing, and points programs reward tight price bands that match the allowance.
Inventory risk moves with distance from the buyer. The further the organization sits from the purchase, the more risk shifts to made-to-order and fulfillment-based models. The closer it sits, the more stock decisions become its problem.
HR workload follows the same pattern: budget and eligibility under company-pays, pricing and exceptions under employee-pays, issuance and reconciliation under points.
A single catalog and single funding rule usually reduce per-site administrative work compared with letting each location run its own store. For organizations still weighing store versus bulk ordering, this company store versus bulk promo order comparison can help clarify whether a portal pays for itself. No model eliminates cost; it relocates cost between cash and administration.
Tax and Accounting Questions to Ask Before Launch
Before launch, put the chosen funding model in front of a qualified tax advisor, not after the store goes live. Treatment of employer-provided merchandise, employee discounts, and points or allowances varies with facts and circumstances, and this article does not reach a conclusion on any of them.
Put these questions in writing: Is the item a benefit, a uniform requirement, or a purchase? Does the employee pay anything? How are discounts documented? If uniforms are part of the mix, the Corporate Apparel Buying Guide for HR and Operations Leaders can help frame that purchase decision. For points programs, ask how unused balances will be tracked and whether they need to appear anywhere in the books.
Accounting and HR should agree on one definition of eligibility and funding before launch. Policy language and store setup should match; mismatches surface later as disputes.
Questions to Settle Before Anyone Designs the Store
Once those tax and accounting questions are in writing, apply the same discipline to the operational decisions. A store design is only as sound as the answers behind it.
- Who is the buyer? Company or employee. Confirm that finance and HR agree in writing, not just in a meeting.
- What is the annual commitment? Model it under each funding option at current headcount, then again at headcount plus 20 percent. A number that only works at today’s staffing level is not a budget.
- Who owns the catalog? Name the person with authority to add or remove items. Shared authority usually produces a catalog that grows without control.
- Who holds unsold stock? Decide who carries discontinued and seasonal inventory, and write the disposition policy before the first order.
- Which policies get published? The Model Three mechanics, in writing for employees.
- Who administers it daily? Assign a named owner and be honest about their available hours. If the answer is “no one has time,” plan for outside management now.
- What does success look like in twelve months? Participation, brand consistency, administrative hours saved, or budget predictability. Pick two, measure them, and skip the rest.
Settle these before a single product is loaded.
Where a Single-Source Partner Fits
Once those questions have answers, the next step is deciding who helps carry them. OneStop Northwest works with organizations across the Pacific Northwest and nationwide on company stores, branded apparel, promotional products, printing, signage, fulfillment, and ongoing program support. Its access to thousands of brands, more than $2 billion in collective buying power, and low or no minimums on many items matters most in models where inventory decisions are consequential. Because the same single-source partner can handle sourcing, decoration, store technology, and fulfillment, the funding model does not have to be rebuilt every time a vendor changes. The practical benefit is fewer handoffs: one team carries the store from funding structure through catalog curation and reordering. Based in Shelton, Washington, OneStop Northwest serves Mason County, Western Washington, and organizations across the country. For related print and collateral work, see How to Choose a Commercial Printing Partner for Ongoing Marketing Collateral.
Conclusion: Choose the Funding Model, Then Build
A single-source partner can carry the build, but the funding decisions still belong to your organization. Start by naming the buyer, the company or the employee, and design catalog, pricing, inventory, and approvals around that answer. Then publish the store policies before launch, as the pre-design checklist directs. Expect cost to move rather than disappear: cash, administration, and inventory risk trade places depending on the model. Bring tax and accounting into the conversation early, and settle the funding structure before anyone starts catalog work. That sequence keeps a good store from becoming an expensive rebuild.
Frequently Asked Questions
A few recurring questions tie these models together.
Who owns inventory risk? Stock versus made-to-order decides much of it. Made-to-order shifts risk to fulfillment; stock sits with whoever funds the buy. Company-pays models carry more stock exposure, while employee-pays and points programs lean toward on-demand ordering.
Are points or allowance programs taxable? Possibly. Treatment depends on facts and circumstances, including funding and use, so involve a qualified tax advisor. No conclusion here.
Benefit or purchase channel? Whichever the funding says. Company pays, it’s a benefit; employees pay, it’s a purchase channel. In practice, one catalog can often serve both, but each purpose follows different rules.
Do we need written store policies for employees? Yes. The pre-design checklist above covers which policies to publish, whatever the model.